Term Insurance
Pure protection for a fixed period, typically offering high cover at relatively affordable premiums. No maturity benefit in standard plans.
Life Insurance
Understand your options, choose the right cover and give your loved ones lasting financial security.
Overview
Life insurance is a contract in which an insurer pays a sum assured to your nominee if you pass away during the policy term, in exchange for premiums. It helps your family manage household expenses, repay loans and stay on track with goals like children’s education.
Some plans also include a savings or investment component. Choosing well means balancing adequate protection with your budget and long-term goals.
Plan Types
Each plan type serves a different purpose. We help you understand which combination suits you.
Pure protection for a fixed period, typically offering high cover at relatively affordable premiums. No maturity benefit in standard plans.
Coverage that can extend to a very high age (often up to 99 or 100 years), helping with legacy and estate planning.
Combine life cover with disciplined savings, paying a maturity benefit as per policy terms.
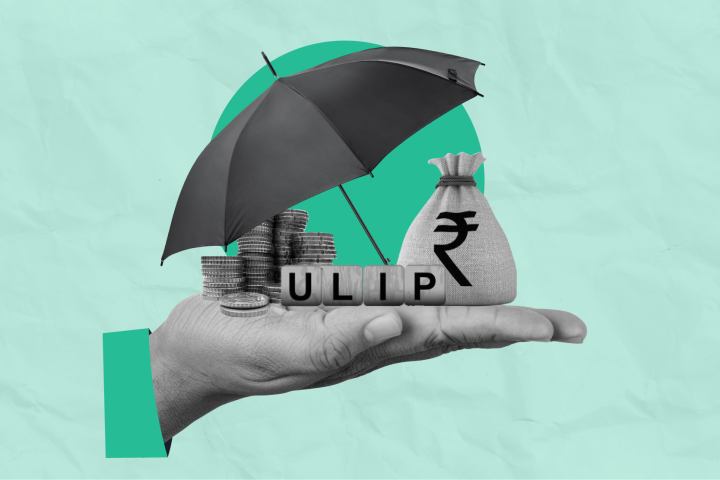
Unit-linked plans that combine insurance with market-linked investment. Returns are not guaranteed and charges apply.
Designed to help secure funds for your child’s education and milestones, even in your absence.
Build a retirement corpus and receive regular income (annuity) after retirement, as per plan terms.
How It Works
We understand your dependants, income, loans and goals.
Compare cover, premiums, features and exclusions side by side.
Help with the proposal form, medicals, KYC and nomination.
Renewal reminders, policy reviews and claim guidance.
FAQs
Term insurance provides pure protection with no maturity benefit in standard plans, usually at lower premiums. Savings plans combine cover with a maturity payout, so premiums are higher for the same sum assured.
Generally, the earlier you buy, the lower the premium tends to be, as premiums are linked to age and health. The right time is when someone depends on your income.
Yes. You can hold multiple policies, but you must disclose existing policies when applying for a new one.
Most policies offer a grace period. If the premium is not paid within it, the policy may lapse. Revival conditions vary by insurer and plan.
Share a few details and we’ll help you estimate a suitable cover amount and compare options.